Saving for a deposit is one of the biggest challenges facing first-time buyers. Now, a proposed government initiative could offer a new way to make buying a home more achievable.
The Your First Home scheme was announced in September 2026 and is expected to help eligible first-time buyers in England purchase a new-build home with a deposit of just 2.5%.
But how would the scheme work? Who could qualify, and what other options are available if you're hoping to buy your first home?
At Hill, we're here to help you understand your options and take the next step towards homeownership. Here's what you need to know about the proposed scheme.
What is the Your First Home scheme?
Your First Home is a proposed government-backed equity loan scheme designed to help eligible first-time buyers purchase a new-build property in England.
The initiative aims to reduce one of the biggest barriers to homeownership: saving enough money for a deposit.
Income limits, local property price caps and mortgage eligibility requirements are also expected to apply.
-
Image
 A 2.5% minimum deposit
Reducing the amount eligible buyers need to save upfront.
-
Image
 A 20% government-backed equity loan
Helping buyers fund part of their property's purchase price.
-
Image
 An initial interest-free period
Intended to help manage the initial cost of the equity loan.
-
Image
 Access to participating developments
The scheme is expected to apply to eligible new-build homes from participating developers.
How much deposit could you need?
The proposed 2.5% deposit is one of the most notable features of Your First Home. For buyers who are struggling to save, reducing the initial amount required could make purchasing a property feel more achievable.
To put this into perspective, here's how a 2.5% deposit compares with a 5% deposit at different purchase prices.
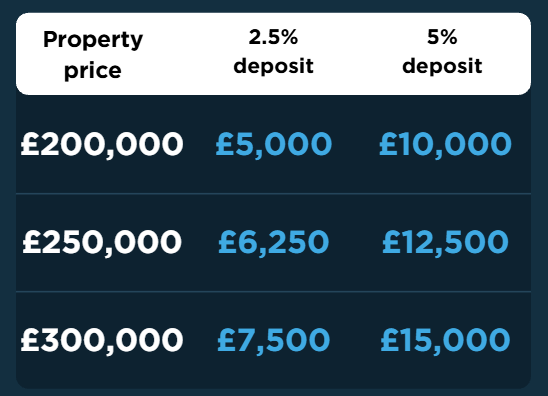
These figures are illustrative only and do not represent confirmed scheme terms or Hill property prices.
For example, on a property priced at £250,000, a 2.5% deposit would be £6,250, compared with £12,500 at 5%.
While a lower deposit could help buyers reach their savings target sooner, it doesn't guarantee mortgage approval or make a property more affordable in the long term. Buyers would still need to meet lender affordability criteria and consider their monthly repayments, fees and other homeownership costs.
How would the Your First Home scheme work?
The proposed scheme is expected to combine a buyer's deposit, a mortgage and a government-backed equity loan.
Based on the headline figures announced so far, the intended structure would comprise:
- 2.5% from the buyer's deposit.
- 20% through the government-backed equity loan.
- The remaining 77.5% through a mortgage.
This is an illustrative breakdown of the proposed structure, rather than a guarantee of the final arrangements.
The equity loan's terms, including the length of the interest-free period and any subsequent charges, will be important considerations for buyers. The final arrangements should be reviewed carefully before deciding whether the scheme is right for you.
Who could be eligible for the Your First Home scheme?
The scheme is intended to help first-time buyers who may otherwise struggle to purchase a new-build home.
It could be worth keeping an eye on if you're:
- Saving for your first property and finding it difficult to build a deposit.
- Hoping to move from renting into homeownership.
- Looking to buy a new-build home in England.
- Exploring ways to make your first purchase more achievable.
However, the final eligibility criteria have not yet been confirmed. Household income caps, local property price limits, lender requirements and restrictions on eligible properties are expected to play a role.
Before making any financial decisions, check the official guidance once the full scheme details are announced.
Can you buy a new-build home with a 5% deposit now?
Yes, some existing mortgage and homebuying options may allow eligible buyers to purchase a property with a 5% deposit, subject to the lender's requirements and the specific scheme's terms.
At Hill, we offer a range of homes and buying options to help buyers explore the route that best suits their circumstances.
-
Explore Deposit Unlock with Hill
Deposit Unlock is an existing low-deposit buying option that can help eligible buyers purchase selected new-build homes with a 5% deposit, subject to participating properties, mortgage availability and the scheme's terms.
If you're hoping to buy before Your First Home becomes available, it's worth exploring whether Deposit Unlock could be suitable for you.
-
Find a new-build home with Hill
Your first home should be somewhere you can picture yourself living, growing and making memories.
Whether you're looking for a contemporary apartment, a home with extra space or a development close to transport links and local amenities, Hill offers a range of homes across London, Essex and Cambridge.
What should first-time buyers do while they wait?
With more information about Your First Home expected at the Budget, there are practical steps you can take now to prepare for your first purchase.
1. Understand your budget. Work out how much you can save and what monthly mortgage repayments you could comfortably afford. Remember to account for legal fees, moving expenses and ongoing household costs.
2. Speak to a mortgage adviser. A qualified adviser can help you understand your borrowing options and whether you might be eligible for an existing low-deposit mortgage or buying scheme.
3. Research available homes. Exploring developments early can help you understand local prices, property types and the options that fit your budget.
4. Compare buying schemes. Consider the eligibility requirements, costs and longer-term implications of each option rather than focusing on the initial deposit alone.
5. Follow the official announcement. The Budget on 28 October 2026 is expected to provide more detail about the Your First Home scheme. Check the published guidance before relying on it as part of your buying plans.
Take your first step towards homeownership with Hill
The proposed Your First Home scheme could offer another route onto the property ladder for eligible first-time buyers, particularly those who find saving a deposit difficult.
Although the full details are still to come, you can start exploring your options today.
At Hill, we're here to help you discover available homes, understand the buying process and explore the support that may be available to you.
Ready to start your homebuying journey?